Last Updated on September 29, 2026 by Bruno Bianchi
Spain taxes for Americans become very real the day you turn into a Spanish tax resident. From that moment, Spain can tax your worldwide income, including U.S. Social Security, 401(k) and IRA withdrawals, Roth IRA distributions and investment gains, even if the money never leaves a U.S. bank or brokerage account.
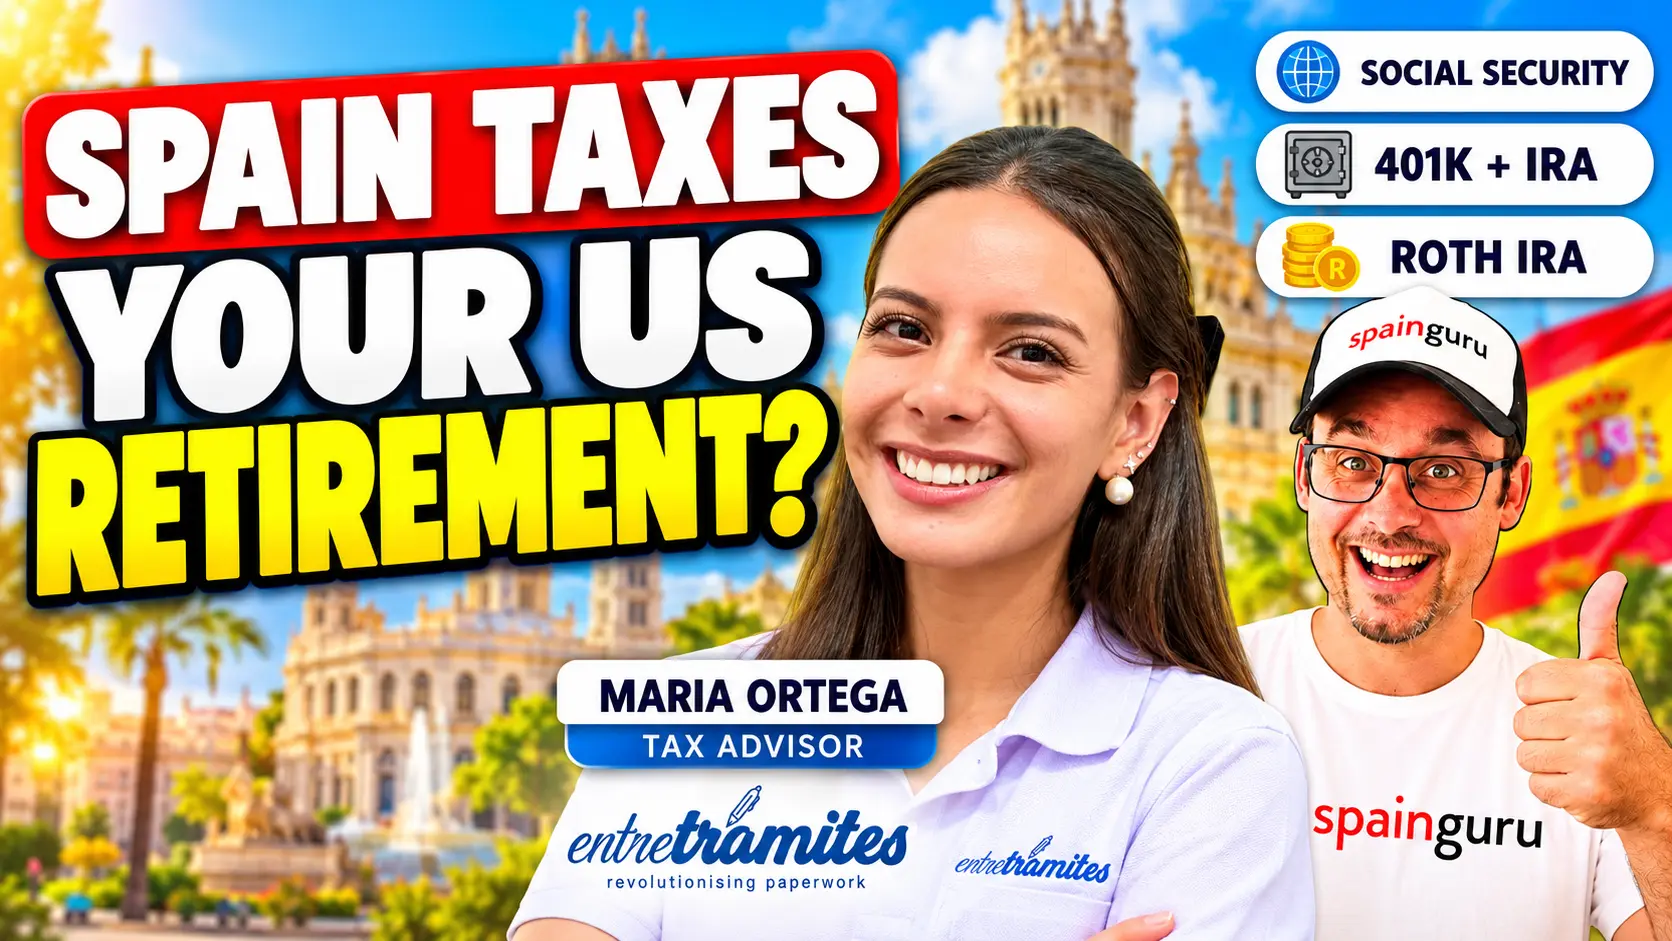
To clear up the most common questions, Bruno from Spainguru interviewed Maria Ortega, tax advisor at EntreTrámites, who works every day with Americans moving to Spain. Below you will find the full video and a structured summary of her answers, from Social Security and Roth IRAs to Modelo 720, wealth tax and the Beckham Law.
Planning your move to Spain?
Get the free step-by-step roadmap — covering visas, budget, housing, and the mistakes to avoid.
Start the Moving to Spain Hub →Let’s start with the interview itself.
Watch the interview: Spain taxes for Americans explained
The conversation lasts about 20 minutes and follows the questions Americans ask most often in the Spainguru community. Each section of this article summarizes one part of the video.
Spain taxes for Americans start with tax residency
Spain considers you a tax resident if you spend more than 183 days in the country during a calendar year, if your main center of economic interests is in Spain, or if your spouse and minor children live here. Once any of these apply, Spain can tax your worldwide income.
As Maria explains in the interview, it does not matter whether you move your bank accounts, pension funds or investments to Spain. Spain has the right to tax them, and on top of paying tax you also take on reporting obligations through informative declarations.
Confused about Spanish taxes?
Spainguru’s vetted tax advisors specialize in expat tax situations — US/Spain treaties, Modelo 720, Beckham Law, and more.
Meet Tax Experts →The planning window closes on January 1
Spanish tax residency works by calendar year. If you will become a tax resident in 2027, Spain looks at your income from January 1, 2027, so any restructuring of your assets should be done before that date.
Maria’s recommendation is simple: plan everything before January 1 of your first year as a Spanish tax resident. After that date, your options to reorganize accounts, realize gains or take withdrawals without Spanish tax consequences shrink considerably. For the residency rules in more detail, see Spainguru’s complete guide to taxes in Spain for expats.
Spain taxes for Americans on U.S. Social Security
U.S. Social Security is one of the most debated items in Spain taxes for Americans. The Spanish Tax Agency (Agencia Tributaria) has issued binding rulings treating it as taxable income in Spain, while some advisors argue it should be exempt with progression, like a U.S. government pension.
EntreTrámites takes the conservative position. In their experience, Social Security is not treated as a public service pension, so the tax agency taxes it as ordinary employment-type income in the general base of the Spanish income tax (IRPF).
Their approach is to declare it normally in the IRPF, use the U.S.–Spain tax treaty to avoid double taxation, and claim a correction later if a better interpretation becomes available.
The risk of the aggressive “not taxable” position
Filing Social Security as exempt when the tax agency considers it taxable can lead to penalties, late-payment interest and fines if your return is reviewed. For a retiree whose main income is Social Security, that exposure can add up over several years.
You can read how members of the community have approached this question in Is U.S. Social Security taxed in Spain?
Spain taxes for Americans on 401(k) and traditional IRA withdrawals
Spain does not treat a 401(k) or a traditional IRA as a tax-advantaged savings vehicle. Withdrawals are taxed as general income at progressive rates, which reach around 47% at the top in many regions.
Maria points out that Spain does not recognize the tax-deferred status these accounts have in the U.S. In practice, the Spanish tax agency will look at the entire withdrawal as income.
Using the treaty to offset U.S. tax paid
If U.S. tax was paid or withheld on the distribution, you can use the treaty to avoid double taxation and credit that tax against your Spanish liability. You still file and pay in Spain, and then claim the amount that has already been taxed in the U.S.
Documents that help you defend your contributions
By default, the tax agency may tax 100% of a 401(k) withdrawal because it has no record of what you contributed versus what the account earned. This is not absolute: you can prove your contributions and ask to be taxed only on the portion that corresponds to growth.
Maria recommends keeping IRS Form 5498, Form 1099-R and the full history of account statements. All of it needs to be converted into euros so the Agencia Tributaria can verify how much you put in and how much the account grew.
If you are still preparing your visa, Spainguru also covers how to document 401(k) funds for the Spain non lucrative visa.
Spain taxes for Americans with a Roth IRA
This is the point of Spain taxes for Americans that causes the most surprise. A Roth IRA distribution that is 100% tax-free in the U.S. is not treated as tax-exempt in Spain.
According to Maria, Roth IRA income is taxed in the savings base of the Spanish income tax. Spain has two bases, the general base and the savings base, and Roth IRA growth falls into the second one.
Savings base rates are progressive and currently range from 19% to 30%, so the larger the gain, the higher the rate. For Americans who built their retirement plan around tax-free Roth withdrawals, this can change the numbers significantly.
Brokerage accounts versus retirement accounts
For a standard brokerage account, wherever it is held, Spain taxes only the gain, meaning the difference between what you invested and what you receive. For a 401(k), the default treatment is to tax the whole withdrawal unless you document your contributions, as described above.
Spain taxes for Americans on government and military pensions
Government pensions are where Spain taxes for Americans work very differently. Federal, military, teacher and civil service pensions are generally taxable only in the U.S. under the treaty. This is the big difference with Social Security, which Spain does tax.
However, Spain still takes these pensions into account through a mechanism called exemption with progression. The pension itself is not taxed in Spain, but it raises the tax rate applied to the rest of your income.
A simple example of exemption with progression
Maria gives this example. You receive a military pension of 40,000 (exempt in Spain) and a private or non-exempt pension of 30,000 euros a year.
Spain will not tax you on 70,000. It will tax only the 30,000, but at the average rate that would apply if your income were 70,000. The exempt pension therefore pushes your taxable income into a higher effective rate.
Note that the treaty rules for government pensions can differ for people who are also Spanish nationals. Veterans can find more detail in Military retirement taxed in Spain: what U.S. veterans need to know.
Veterans’ and disability benefits
U.S. disability or veterans’ benefits are not automatically exempt in Spain. Everything depends on how Spain classifies the benefit under its own legal definition of permanent disability, even if the U.S. already recognizes it as such.
EntreTrámites recommends requesting a formal equivalency review with the Spanish tax agency so your pension is classified correctly before you assume it is protected.
Modelo 720 and wealth tax: Spain taxes for Americans with savings abroad
Once you are a Spanish tax resident, you must file Modelo 720 if any category of your assets held abroad exceeds 50,000 euros on December 31. The three categories are bank accounts, securities and investments (including insurance and pension products), and real estate. Crypto held abroad is reported separately on Modelo 721.
Modelo 720 is informative, not a tax
Maria stresses that Modelo 720 does not make you pay anything by itself. It is an informative declaration of assets located outside Spain, filed between January 1 and March 31 of the following year.
Her short answer on retirement accounts is clear: 401(k)s, IRAs, Roth IRAs and investment accounts need to be reported if the category exceeds the 50,000-euro threshold, regardless of how they were treated in the past. For a full walkthrough, read Spainguru’s Form 720 essential guide for expats and the community discussion on whether 401(k)s must be reported on Modelo 720.
Wealth tax depends on your region
These account balances also count toward Spain’s wealth tax. The outcome depends heavily on where you live, because regions such as Andalusia, Catalonia, Valencia and the foral communities apply different allowances, rates and reliefs.
Choosing your region is therefore part of planning your Spain taxes for Americans, not only a lifestyle decision.
Timing withdrawals to reduce Spain taxes for Americans
Taking one large withdrawal while you are a Spanish tax resident usually pushes that income into a higher bracket, because Spain sees it as a single one-off payment in that tax year. Spreading withdrawals over time generally keeps the rate lower.
If a large withdrawal is unavoidable or simply your preferred option, Maria recommends taking it before you become a Spanish tax resident. In that case it is taxed only in the U.S. and does not need to be declared in Spain. The same logic applies to realizing gains you already plan to take.
Can the Beckham Law help Americans moving to Spain?
The Beckham Law is a special tax regime for people who move to Spain for work. It taxes employment income earned while living in Spain at a flat 24% (up to 600,000 euros) and largely shields income and assets held outside Spain from Spanish taxation.
Maria clarifies that remote work counts as work performed in Spain. If you live in Spain and work for foreign clients or a foreign company under the Beckham Law, that salary is still taxed at 24% in Spain.
Retirees cannot use the Beckham Law
If you are fully retired and living on your pension, 401(k), IRA or Roth IRA, the Beckham Law is not available. It requires a qualifying work connection with Spain, such as a Spanish employment contract, being a director of a Spanish company or another eligible activity.
If you meet that requirement, you can apply even if you already receive a pension. You must apply within six months of starting your activity in Spain and not have been a Spanish tax resident in the previous five years. Spainguru’s Beckham Law guide covers all the requirements.
When the Beckham Law costs more than it saves
Under the Beckham Law you cannot use double taxation treaties, and you lose the personal and family deductions available under the standard regime. A Spanish payroll also brings employee Social Security contributions.
For some people the regime becomes an expense rather than a saving. That is why EntreTrámites always runs a tax projection comparing both regimes before recommending one.
Planning Spain taxes for Americans before the move
The common thread in Maria’s answers on Spain taxes for Americans is timing. Most of the costly mistakes she sees come from Americans who become Spanish tax residents first and look at their accounts afterwards.
Before you move, it is worth reviewing which income will be taxed in the general base and which in the savings base, whether any withdrawals or gains should happen before January 1, how your region’s wealth tax applies to you, and which reporting forms you will need to file. The Spain tax calculator can give you a first estimate, and a simulation with a cross-border advisor gives you the real numbers.
Remember that U.S. obligations continue as well, since the U.S. taxes its citizens wherever they live. Settleguru’s American expat tax guide covers FBAR, FATCA and the rest of the U.S. side.
Frequently asked questions about Spain taxes for Americans
Is U.S. Social Security taxed in Spain?
According to EntreTrámites, yes. The Spanish tax agency treats it as taxable income in the general base, and the U.S.–Spain treaty is used to avoid double taxation.
Is a Roth IRA tax-free in Spain?
No. Spain does not recognize the Roth IRA’s tax-free status. Distributions are taxed in the savings base at rates from 19% to 30%.
Are U.S. military and government pensions taxed in Spain?
Generally they are taxable only in the U.S. under the treaty, but Spain applies exemption with progression, so they increase the rate applied to your other income.
Do I need to report my 401(k) on Modelo 720?
Yes, if the category that includes it exceeds 50,000 euros on December 31. Modelo 720 is an informative return and does not trigger tax by itself.
Can retirees use the Beckham Law?
No. The regime requires a qualifying work or business connection with Spain. Fully retired people living on pensions and investment accounts cannot apply.
Where to get advice on Spain taxes for Americans
Spain taxes for Americans are never one-size-fits-all. Every case depends on the type of income, the account, your nationality and the Spanish region where you will live. If you want advice on your own numbers, you can book a consultation with EntreTrámites, or compare other cross-border specialists on Spainguru’s page of tax experts for Spain and U.S. filings.
If you would like to understand the basics before booking a consultation, Bruno also hosts a free monthly Spanish Taxes webinar. It covers the Spanish income tax (IRPF), wealth tax, the Beckham Law and key planning strategies, with live time for your questions.
Here you can find Spainguru’s recommended services for Spanish visas: https://spainguru.es/services-for-spanish-visas/
Join Spainguru’s American Expats in Spain Facebook group here: https://www.facebook.com/groups/americanexpatsinspaingroup
Conclusion
Spain taxes for Americans follow different logic than the U.S. system. Social Security and 401(k) withdrawals are taxed as general income, Roth IRAs lose their tax-free status, government pensions are exempt but still raise your rate, and Modelo 720 and wealth tax add reporting and regional considerations.
The single most valuable step is to plan before January 1 of your first year of Spanish tax residency. If you are moving on a visa such as the Spain non lucrative visa, build a tax projection into your relocation plan from the start.
This article is for informational purposes and reflects the interview with EntreTrámites alongside publicly available sources. It is not legal or tax advice. For professional guidance, consult expert advisors, see https://spainguru.es/services-for-spanish-visas/.
Get your free step-by-step Spain move plan
10 emails over 2 weeks covering visas, budget, housing & the mistakes to avoid.
Free, from the team behind a community of 225,000+ expats.
100% free · No credit card · Unsubscribe anytime